What the Return of No-KYC Crypto Cards Really Signals for Builders
Originally published in The  Collateral on LinkedIn.
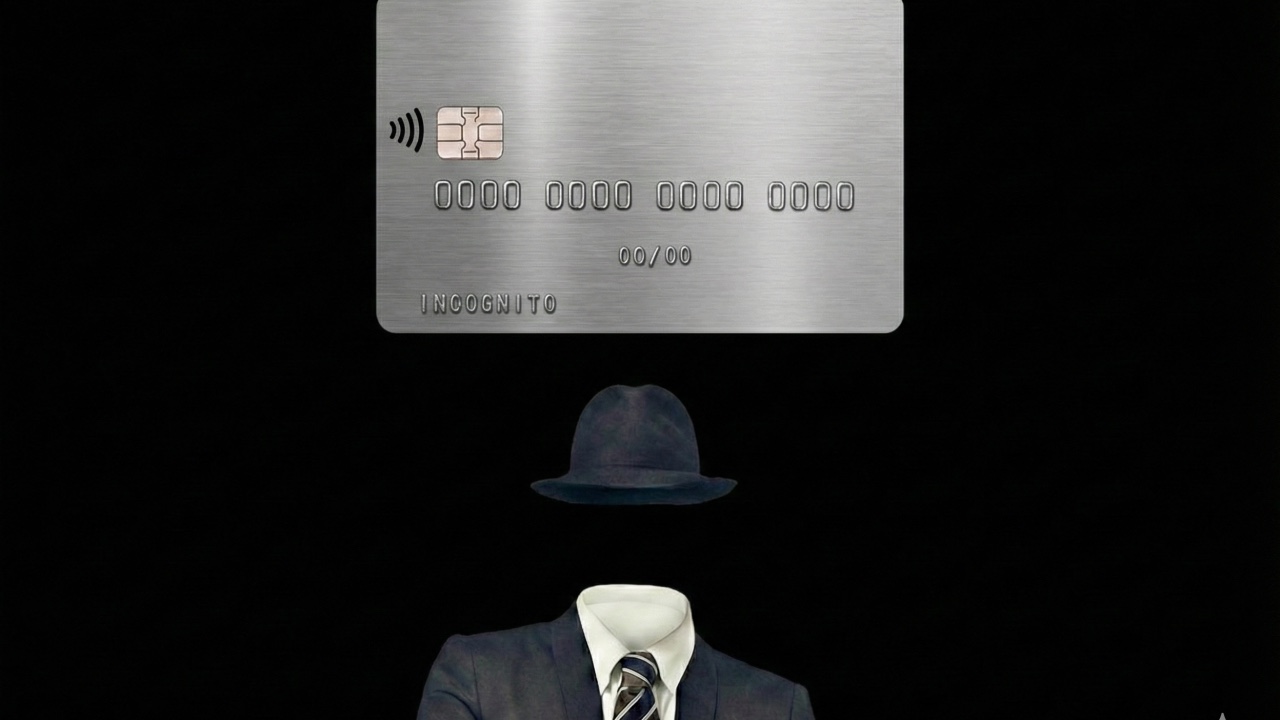
Every few months, “no-KYC” or “low-KYC” crypto cards resurface across social media. The promise is familiar: instant issuance, global acceptance, massive limits, zero friction.
And the outcome is just as familiar.
The programs shut down.
What is circulating today is not innovation. It is the same structural shortcuts, repackaged with a privacy narrative and more polished marketing.
At BCS, we have watched this cycle repeat often enough to be clear about one thing: If a card program optimizes for speed over structure, it is already operating on borrowed time.
The Two Models That Keep Failing
1. Single-Load “Gift Card” Products Marketed as Crypto Cards
These are prepaid cards that can be loaded once and spent until the balance runs out. The only real change is the funding method. Crypto replaces fiat.
They are often promoted as:
- Global
- Privacy-focused
- No-KYC
In practice:
- Merchant acceptance is inconsistent
- Balances frequently remain stranded
- Unspent funds quietly become part of the revenue model
The underlying card product has not evolved. Only the messaging has.
2. Corporate Card Programs Repackaged for Consumers
This model is more sophisticated and far riskier.
Corporate card programs are built for businesses, not individuals. They are designed with:
- Extremely high spending limits
- Global usage flexibility
- High interchange economics
When these programs are resold to consumers with minimal controls, they appear compelling at launch. They also draw rapid attention from issuers, networks, and regulators.
When these programs fail, they do not wind down gracefully. They stop abruptly.
The Question Builders Should Actually Be Asking
The question is not:
How fast can I issue cards?
The real question is:
Will this program still be operating in 18 months?
If the answer relies on:
- Regulatory blind spots
- Jurisdictional arbitrage
- Temporary enforcement gaps
Then the infrastructure is not durable. It is provisional.
Compliance Is Not a Feature. It Is the Foundation.
At BCS, we design card programs with the assumption that:
- Oversight will increase
- Rules will tighten
- Regulators will eventually look closely
That assumption changes everything.
It means:
- Realistic limits from day one
- Proper KYC and AML pathways
- Multitenant infrastructure designed for compliance
- Risk management prioritized alongside growth
This is not about moving slowly. It is about being commercially ready.
Why BCS Starts Small on Purpose
Many card programs fail because they try to appear global and limitless from day one.
BCS takes a different approach:
- Controlled rollouts
- Clear user segmentation
- Transparent program rules
- Infrastructure that scales without breaking compliance
Starting small is not a constraint. It is how sustainable financial products are built.
The Bottom Line
If a crypto card program’s primary selling point is what it avoids requiring, that should raise concerns.
The programs that survive are not the fastest to launch. They are the ones designed to hold up when scrutiny arrives.
At BCS, longevity is not a marketing claim. It is the design principle we start with.