Why Card Programs Are Failing and What Will Survive
Originally published in The  Collateral on LinkedIn.
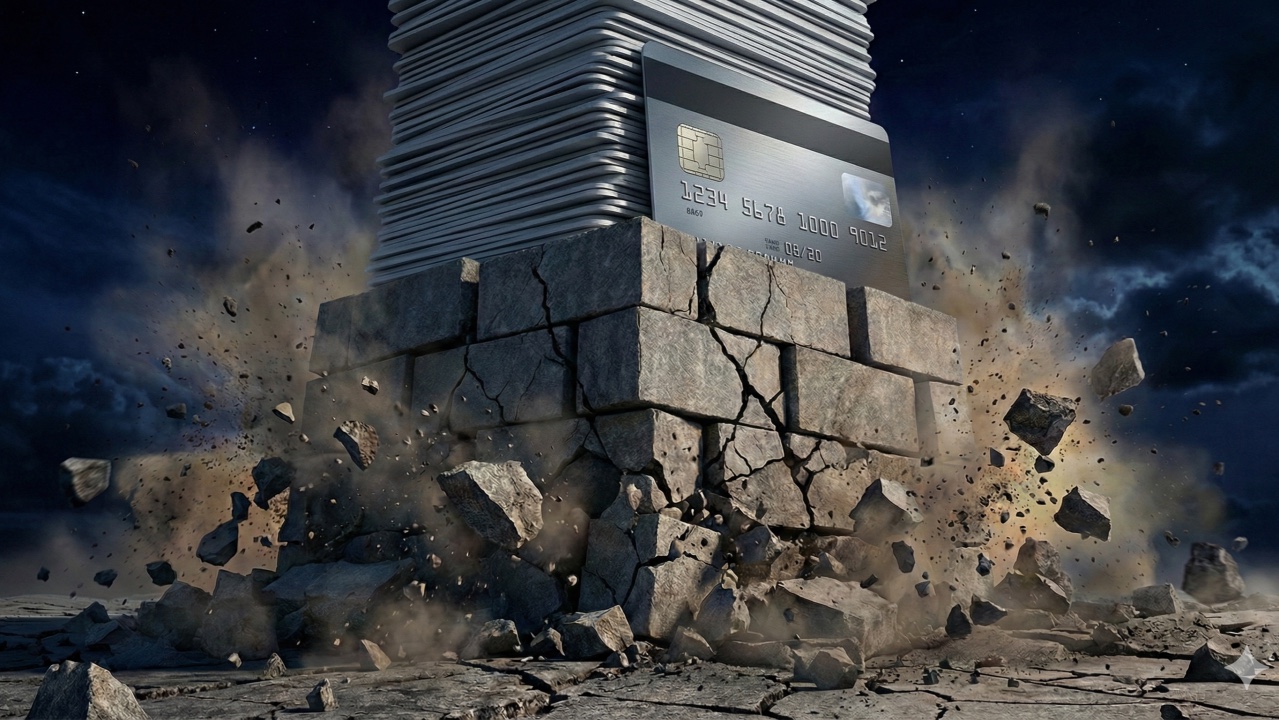
In recent months, a number of card programs have gone offline with little warning.
Not because users disappeared. Not because products failed. But because the infrastructure underneath them was not ready for real-world scrutiny.
This is not a downturn. It is a reset.
What is being filtered out
The issuers that treated compliance as an afterthought are being cleaned out.
Not selectively. Structurally.
For a long time, parts of the ecosystem optimized for the fastest launch, the lowest cost, and the widest promise set.
Many programs chose partners based on what sounded good in a pitch deck, not on commercial readiness.
That tradeoff is now surfacing publicly and expensively.
The lesson for builders
Programs that prioritized speed, price, or popularity alone are learning a hard truth.
Not everything promised is true. And not everything that works at launch survives contact with regulators, banks, and scale.
When infrastructure fails:
- Cards stop working immediately
- Users lose trust just as fast
- Teams inherit problems they did not design for
These risks do not show up in feature lists. They show up in outcomes.
What actually lasts
What emerges on the other side of this correction will be fewer players, higher standards, compliance-first operating models, and more sustainable business designs.
This is not about being conservative. It is about being structurally sound.
Why starting small matters
The strongest programs do not try to do everything on day one.
They start with a narrow, well-defined use case. They prove compliance and operational discipline early. They build trust with users, banks, and regulators. They expand only once the foundation is proven.
Commercial readiness beats ambition every time.
The BCS approach
At BCS, we believe card programs should be built for longevity, not just launch.
That is why we provide:
- Multitenant infrastructure with optional, vetted issuers across jurisdictions
- A risk management and compliance-first framework embedded from day one
- Backend infrastructure that abstracts complexity instead of pushing it onto product teams
BCS offers everything a co-branded card launch needs to engage users today, operate under scrutiny, and build a program that sticks while remaining expandable as products and markets evolve.
Our philosophy is deliberate. Spend first. Expand second.
That is why we focus initially on spend use cases and then evolve into loan-to-spend products only once compliance, risk, and operational layers are ready.
The real decision builders face
Choosing a partner should not be dictated by the fastest solution, the cheapest offer, or the most popular name.
It should be dictated by who understands the industry inside out, who has the structural parts in place, who expects scrutiny instead of reacting to it, and who will still be there when the rules tighten again.
A final thought
This reset is not over, but its direction is clear.
If you are building for the long term, choose partners who are too.
Partners who invest in compliance readiness, risk management, and infrastructure before they are forced to.
That is how card programs stop breaking and start lasting.